TransUnion®

Screenshots
Details
- Rating
- 3.06K reviews
- Version
- 5.8.0
- Developer
- TransUnion Interactive, Inc.
Analysis by Norviv
Checking credit information on a phone sounds simple, but the experience depends on how clearly an app presents reports, scores, and related offers when you actually need them. I spent time with TransUnion®, a free finance app from TransUnion Interactive, Inc., and found that its main value is convenience: it puts important credit information in a mobile format instead of making you begin every check from a desktop browser.
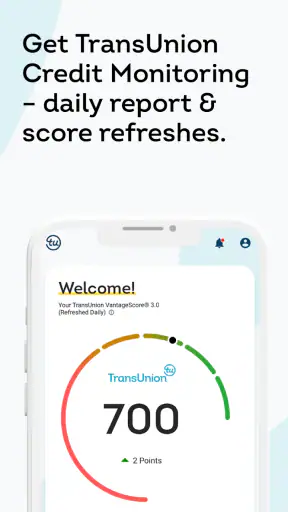
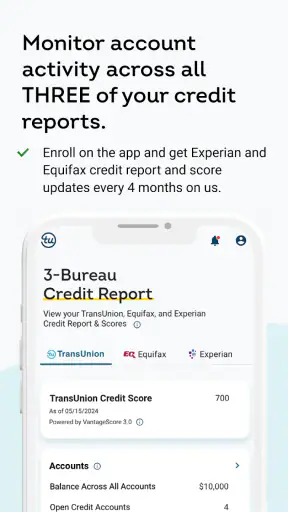
The app is aimed at people who want a practical view of their credit position, especially before applying for a card, arranging finance, reviewing personal finances, or checking whether recent activity appears as expected. Its store summary focuses on scores, reports, and offers, and that is a fair description of the experience. It is not a full replacement for every financial tool, but it can be useful as a focused place to review credit-related information.
How TransUnion® feels during everyday use
I find the everyday experience easiest to judge when I arrive with one clear question, rather than treating the app as a place to browse aimlessly. That small habit helps me separate a quick score check from the slower work of reading a report, and it makes interruptions less frustrating. It also sets up a closer look at what changes when a session becomes more demanding.
Speed expectations when you open the app
My first impression is that the app is built for short visits rather than long sessions. I would open it to check a score, look through a report, or review an offer, then leave once I had answered the question that brought me there. That narrow purpose helps the experience feel more manageable than a broad banking app filled with balances, transfers, budgeting tools, and notifications.
Perceived speed matters here because financial information is usually time-sensitive. If I am preparing an application or trying to understand a change in my credit position, I do not want to hunt through unrelated screens. The focused nature of TransUnion® makes the journey easier to understand, although the amount of information in a credit report can naturally make a session feel more involved than checking a single account balance.
The current version is 5.8.0, and the app requires at least OS 10. That requirement makes the first practical question straightforward: your phone needs a reasonably current operating system before you can judge the app itself. On a supported device, I would expect the main experience to be most comfortable when the app is used for one clear task at a time rather than treated as an all-day finance dashboard.
What happens during heavier use
The demanding moments are not likely to come from constant background activity or complex calculations on the phone. They come when I move through detailed report information, compare several parts of my credit picture, or pause to interpret what an offer means for my situation. In those moments, the challenge is less about flashy performance and more about keeping the presentation readable and the next action obvious.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
A useful workflow is to decide what I am checking before opening the app. For example, if I am reviewing a possible error, I would first note the account or activity that concerns me, then use the report to look for the relevant entry instead of scrolling without a plan. This makes the session feel faster and reduces the chance that I confuse a general score view with the underlying report details.
I also would not treat an offer screen as the destination of the review. Offers can be relevant, but they should be considered separately from the factual task of understanding a report or score. My practical approach is to finish the credit check first, write down anything that needs attention, and only then decide whether an offer deserves further thought. That separation is one of the easiest ways to avoid rushing through a financial decision.
Reliability and confidence in the information
For a finance app, reliability is about more than whether a screen loads. I want the information to be presented consistently, the report to remain understandable when I return to it, and the app to help me distinguish a headline score from the broader details behind it. TransUnion® is most useful when I treat it as a monitoring and review tool, not as a promise that one number explains every lending decision.
That distinction is important for anyone comparing the app with a bank application. A bank app may show a credit-related score as one small part of a wider account experience, while this app is centered on credit information. The trade-off is focus: I get a more direct credit-oriented visit, but I still need to use sound judgement when interpreting the result and considering an application elsewhere.
Its audience size suggests that the app is not a niche experiment. It has more than a million installs, with an average rating of 3.2 from roughly 8.4 thousand ratings and about 3.1 thousand written reviews. I read that combination as a reason to keep expectations balanced. Many people clearly find a reason to install it, but the rating also warns me that the experience may not feel equally smooth or satisfying for everyone.
When an app handles personal financial information, I prefer a calm, deliberate routine. I check the information I came for, avoid making a decision solely because an offer is visible, and keep a separate note of questions I may need to investigate. That habit is more valuable than repeatedly refreshing the same screen, especially when I am trying to understand a change rather than simply glance at a score.
Device constraints and practical comfort
The minimum OS requirement of 10 is worth checking before installation, particularly if the phone is older or has not been updated for some time. A device that cannot meet that requirement is not a performance problem in the ordinary sense; it is a compatibility barrier. For supported phones, the more relevant concern is whether the screen is comfortable for reading dense financial information.
Credit reports are not naturally light reading. On a smaller display, I would expect more scrolling and a greater need to slow down when checking names, dates, balances, or account entries. That does not make the app unsuitable for a phone, but it does change the best use case. I would use it for a quick review or a targeted investigation, then move to a larger screen if I needed to compare many details side by side.
Resource demands also seem easier to manage when the app is used intentionally. I would not keep it open while doing unrelated tasks, because there is little benefit in treating a credit checker like a messaging or navigation app. Open it when needed, complete the review, and close it. That routine keeps the app’s role clear and avoids turning a focused finance tool into another source of screen clutter.
Recovery is another practical consideration. If a session is interrupted, I would return with the exact question in mind rather than assuming I should repeat every step from the beginning. For example, after a phone call or a break, I would go back to the report section I was checking and confirm the relevant detail again. This is slower than relying on memory, but it is safer when the information could influence a financial application.
A realistic credit-check scenario
Imagine I am preparing to apply for a new financial product and want to understand my current position first. I would open TransUnion®, begin with the score view to get a general sense of where I stand, and then move into the report rather than stopping at the headline figure. I would look for anything unfamiliar, record the details that need clarification, and avoid interpreting an offer as a recommendation simply because it appears beside the credit information.
If the report looks familiar, the app has done its job as a quick preparation step. If something looks wrong, the value is in identifying the exact entry and gathering enough information to investigate it through the appropriate channel. The app cannot replace careful follow-up, but it can make the first review less intimidating than starting with a vague feeling that something may be off.
A second useful scenario is routine personal organization. Instead of checking credit only when I am about to apply for something, I could use a planned review to notice changes and keep my own financial records aligned. The important tip is to compare meaningful details over time without obsessing over every small movement. A score is a snapshot; the report context is what helps me ask better questions.
Where it beats usual alternatives
The usual alternative is a bank app, a desktop browser, or a general personal-finance service. A bank app is convenient when I am already checking transactions, but credit information may be only one small feature among many. A browser can offer a larger layout, yet it is less convenient when I want to check something away from a computer. A broad finance service may combine budgeting and accounts, but that wider scope can make a focused credit review feel less direct.
TransUnion® makes the most sense when I want the credit task to stand on its own. That focus is its clearest advantage. I do not need a budgeting interface to answer a report question, and I do not need to mix credit review with everyday banking. The compromise is that I should not expect it to become my complete financial command center.
I would also be cautious about choosing it solely because it is free. Free access removes an obvious cost barrier, but the real question is whether the app’s presentation suits the way I make financial decisions. Someone who wants a detailed desktop comparison, advanced budgeting, or a single place for every account may prefer another option. Someone who wants a direct mobile route into credit information is more likely to appreciate this one.
Who should use it, and who should skip it
I would recommend it to people who want a dedicated mobile way to review credit scores and reports, especially before a major financial step. It can also suit users who prefer checking information in short sessions and keeping the rest of their finances in separate tools. The Everyone age rating makes it broadly accessible from a content perspective, though younger users should still understand that credit information requires careful interpretation and responsible decisions.
I would skip it if I mainly need expense tracking, bill management, investment research, or a complete household budget. Those needs belong to different kinds of finance tools, and adding a credit-focused app will not solve them. I would also choose a larger-screen option when I need to study many report entries at once or compare documents in detail.
People who dislike sorting through financial terminology may find the report experience demanding. My advice is not to rush. Read one section at a time, separate the score from the supporting report, and write down unfamiliar items before taking action. That workflow turns the app from a number-checking shortcut into a more useful review step.
My performance verdict
After using it as a focused finance app, I see TransUnion® as a practical companion for credit checks rather than a complete financial workspace. Its strongest quality is the directness of its purpose: scores, reports, and offers are brought together in a mobile experience that can fit naturally into a quick review before an application or a personal finance check.
Its limitations are just as important. Dense report information can require patience, a small phone screen may not be ideal for extended investigation, and the moderate average rating suggests that the experience has not been perfect for every user. I would approach it with realistic expectations about speed and recovery: use it for targeted sessions, allow time to read carefully, and return to the relevant section if an interruption breaks the flow.
Overall, I think it is worth trying if your main question is, “What does my credit information look like right now?” It is less convincing if your question is, “Can this replace all my other finance apps?” For my own use, the best habit is to treat the app as an informed starting point: check the score, inspect the report, separate offers from facts, and make decisions only after understanding the details. That is where this free credit-focused tool provides its most useful value.
Frequently Asked Questions
01What is the TransUnion® app used for?
The TransUnion® app is designed to help users monitor and understand their credit information from a mobile device. Depending on the plan and region, it may provide access to credit reports, credit scores, alerts about changes, identity-protection tools, and educational resources. Available features can vary, so reviewing the app’s current description and subscription details before downloading is recommended.
02Is the TransUnion® app free to download and use?
Downloading the TransUnion® app is generally free, but some features may require registration, a paid membership, or an eligible TransUnion® service. Free access, trial periods, pricing, and included tools can differ by country and may change over time. Before starting a trial or subscription, check the billing terms, renewal conditions, and cancellation instructions shown in the app.
03What information is required to create a TransUnion® account?
To use the app, you may need to provide personal details such as your name, address, date of birth, email address, and other information needed to verify your identity. TransUnion® may also ask security questions or request additional verification to protect your credit file. Enter information carefully and only use the official app downloaded from a trusted store.
04Can TransUnion® help me detect identity theft or changes to my credit file?
The app can provide monitoring alerts when certain activity or changes are detected in your TransUnion® credit information, depending on your location and membership. These alerts may help you notice unfamiliar accounts, inquiries, or other suspicious activity, but they do not prevent every type of fraud. If something looks incorrect, review the details and follow TransUnion’s official dispute or fraud-reporting guidance.
05Does using the TransUnion® app affect my credit score?
Checking your own credit report or score through the TransUnion® app is generally considered a soft inquiry and should not lower your credit score. However, the app itself does not improve a score automatically, and applying for credit through another service can create a hard inquiry. Credit scores may also differ between lenders because they use different scoring models and credit-report data.


